Quick answer
Purchase order finance pays your supplier so you can fulfil a confirmed customer order that's larger than your cash can cover. The financier relies heavily on the customer's purchase order and the supplier's ability to deliver, and is repaid when your customer pays. It suits distributors and resellers with large, one-off orders from reliable customers. Alternatives include a short-term cash flow loan, a line of credit or property-secured lending.
Key points
- Funds supplier costs for a confirmed customer order
- Relies on the customer's reliability and the supplier's delivery
- Repaid when the customer pays the invoice
- Cash flow loans or property-secured lending can be simpler alternatives
- Trigger
- Confirmed customer order
- Repaid by
- Customer payment
- Alternatives
- Cash flow or secured loan
- Enquiry
- No credit check
What is purchase order finance?
You’ve won a big order. The customer has signed. Now there’s a problem: to fill it, you need to pay your supplier first, and the amount is more than your bank account or usual facilities can handle.
Purchase order finance solves exactly that. A financier pays your supplier, the goods are delivered to your customer, you invoice, and when the customer pays, the financier is repaid and you keep the margin. It’s built around a single transaction rather than your business’s overall borrowing capacity.
Who is it for?
It suits businesses with a particular shape:
- You buy finished goods and resell them, like a distributor, wholesaler or importer.
- Your customer is reliable, such as an established business, a large retailer or a government body.
- The order is bigger than usual, so normal cash flow can’t fund it.
It suits less well when you heavily transform raw materials, when the customer is a consumer, or when the order is routine and could be handled with a standing facility like a line of credit.
How does the money move?
| Step | What happens | Who pays whom |
|---|---|---|
| 1 | Customer issues a purchase order | — |
| 2 | Financier pays your supplier | Financier → supplier |
| 3 | Goods delivered to your customer | — |
| 4 | You invoice the customer | — |
| 5 | Customer pays | Customer → financier (or you) |
| 6 | Financier takes its amount and fees; balance to you | Financier → you |
The details differ between providers, but that’s the shape. Some businesses then pair it with invoice finance to shorten step 5.
What are the alternatives?
Purchase order finance is specialised, and sometimes a simpler product does the job:
- A short-term cash flow loan, typically $5,000 to $500,000 for trading businesses, sized on turnover. See cash flow loans.
- A line of credit, if big orders are becoming a regular part of the business.
- Property-secured lending, from $20,000 to $5,000,000, if the order is very large or the business is newer.
A specialist can compare these with you in one call. You can request that call here. There’s no credit check involved in asking.
What could go wrong, and how do I protect myself?
Three risks deserve attention:
- Supplier failure. Late, short or faulty deliveries can derail the deal. Use suppliers you know, and check quality before goods ship where possible.
- Customer cancellation or delay. Read the purchase order or contract. What are the cancellation terms? What happens if delivery is a few days late?
- Thin margins. If the margin is slim, finance costs and any hiccups can eat it entirely. Run the numbers on a bad-case scenario, not just the expected one.
Business.gov.au’s guide to managing cash flow stresses clear payment terms and planning ahead. For a big order, that means agreeing the customer’s payment terms before you commit to the supplier.
An illustrative example
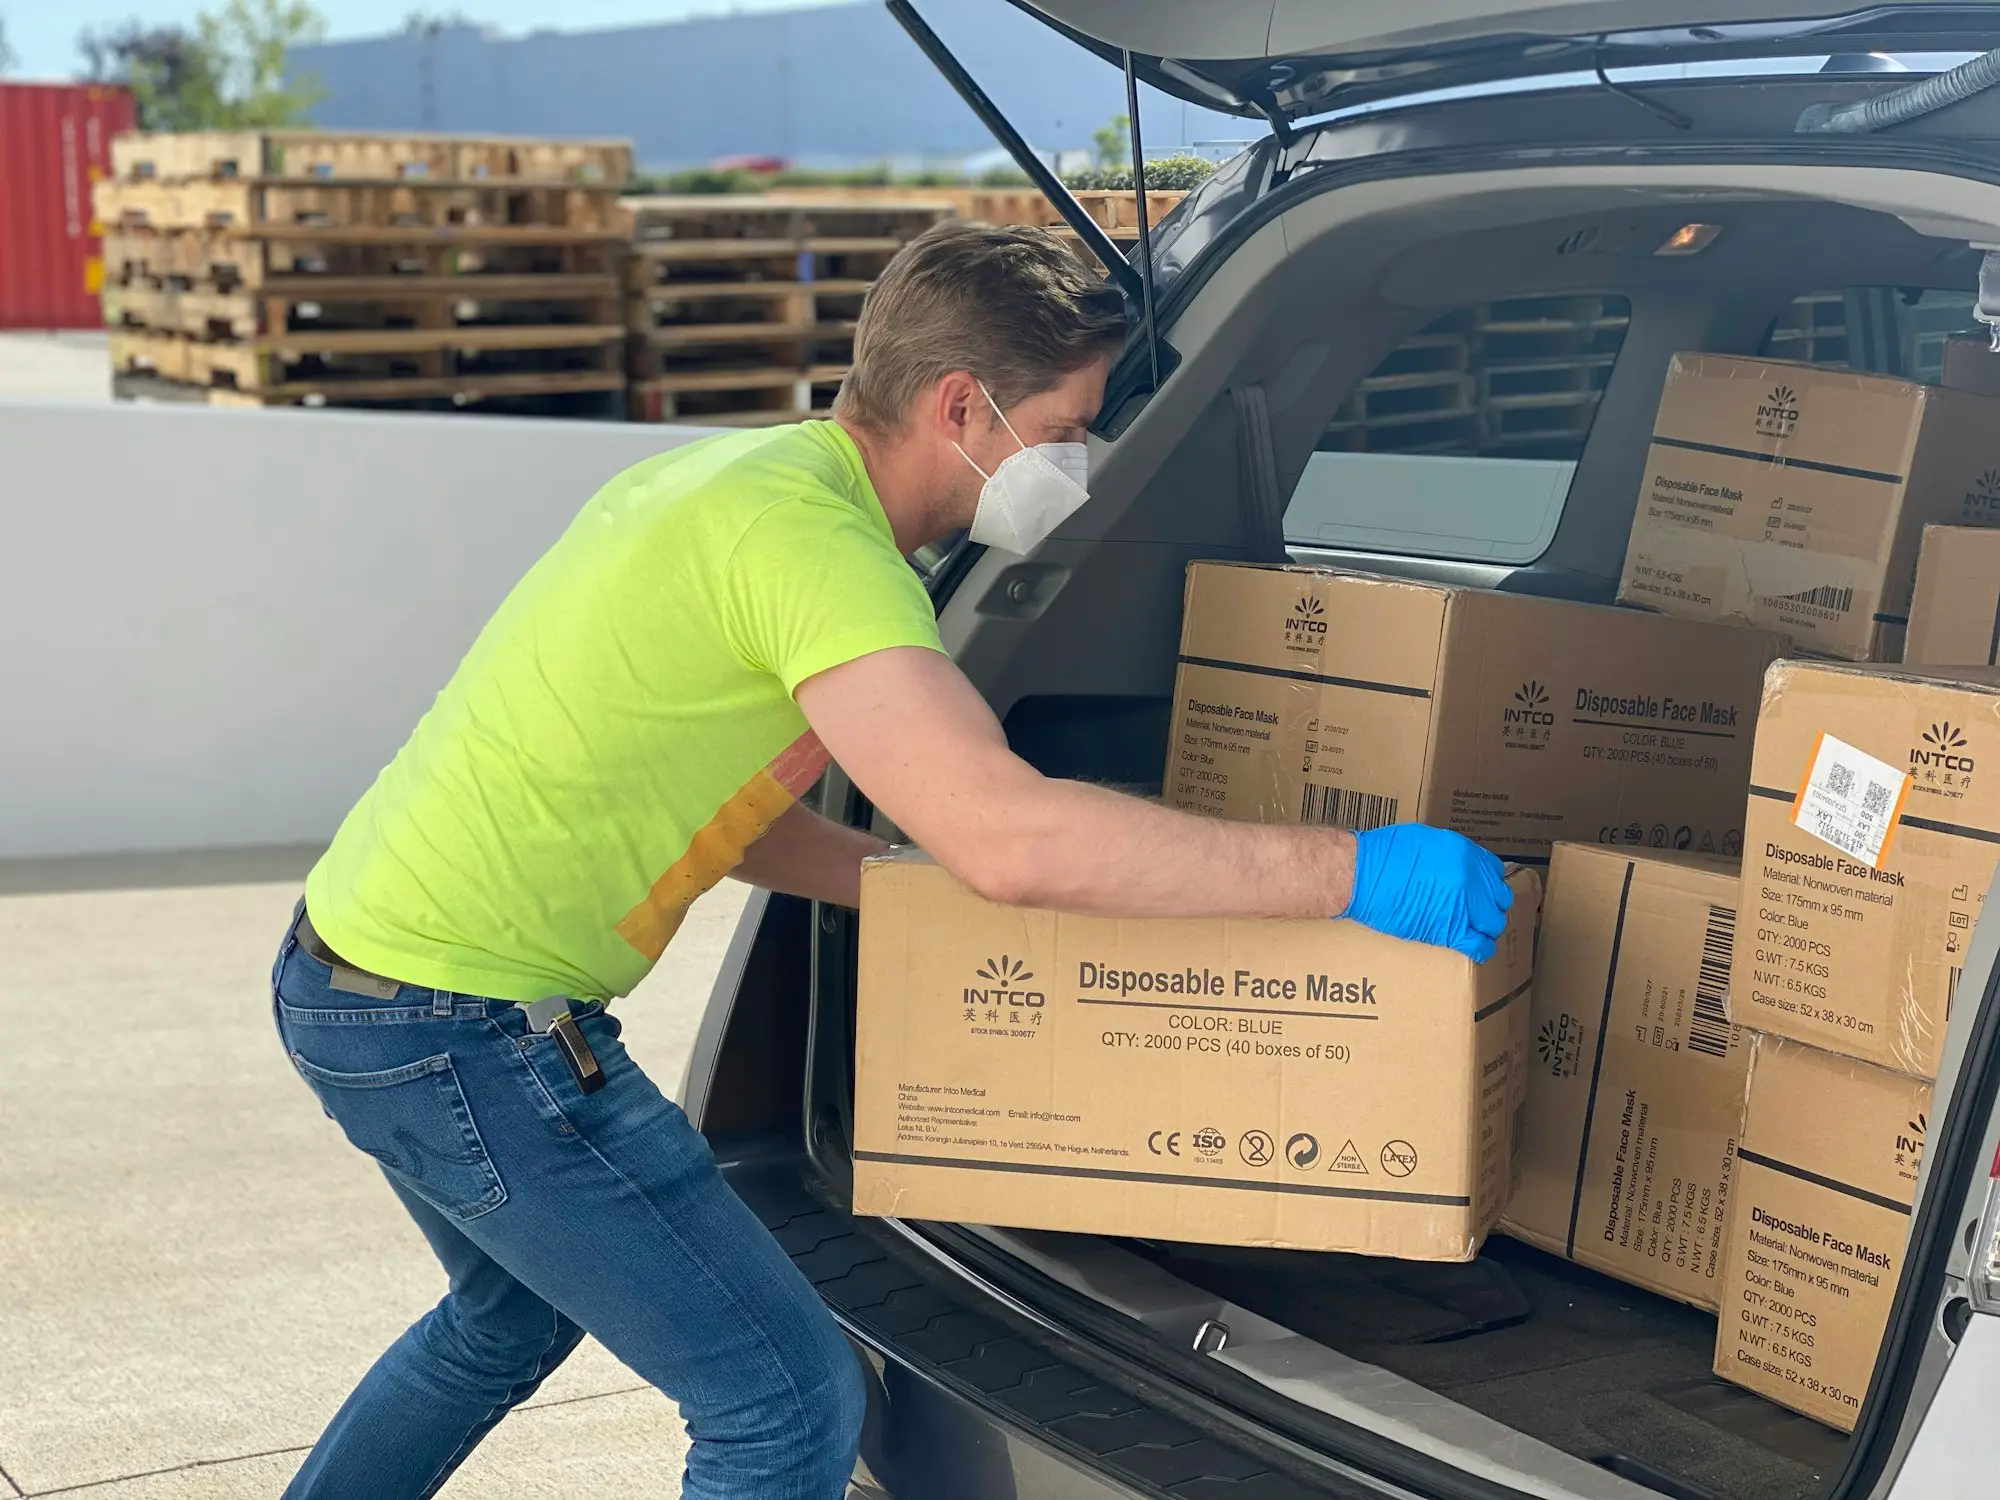
Illustrative only. A small distributor of commercial cleaning products wins a supply contract with a regional hospital network. The first order is triple its usual monthly volume, and the manufacturer wants payment before dispatch. The hospital network pays on 30-day terms. Purchase order finance pays the manufacturer, the distributor delivers and invoices, and the hospital’s payment clears the facility. The distributor’s own cash stays free for wages and other customers.
Is purchase order finance right for repeat orders?
If big orders are becoming a regular part of your business, it’s worth stepping back. Purchase order finance is designed around individual transactions, which suits one-off or occasional large orders. When large orders arrive every month, a standing facility often works better:
- A line of credit gives you a limit to draw on for each supplier payment, repaid as customers pay. See business line of credit.
- Trade or stock finance suits ongoing purchasing from regular suppliers. See stock finance.
- Invoice finance shortens the wait once goods are delivered and invoiced. See invoice finance.
The shift from one-off to recurring is a good moment to review your whole working capital picture. Growing businesses often find that their supplier terms, customer terms and stock levels need to change together. Mapping the full cycle, as described on our working capital loans page, helps you choose a structure that grows with you rather than one you have to re-arrange for every order.
What documents does a purchase order deal need?
Because the financier relies on the transaction, the paperwork centres on the order itself. Expect to provide:
- The customer’s purchase order or contract, signed, with quantities, prices, delivery terms and payment terms
- The supplier’s quote or pro forma invoice, matching the order
- Evidence of your track record, such as previous similar orders delivered on time
- Details of the customer, so the financier can assess their reliability
- Your business details and bank statements, as with most business finance
Having these ready, and making sure the numbers line up across all of them, is the quickest way to get a deal moving.
Big order, small cash? There’s usually a way
Winning a big order should feel like a win, not a crisis. Our page on winning a big contract looks at the wider picture, including staff, equipment and working capital.
When you get in touch, there’s no credit check at enquiry. A real person reads your situation and calls you, and your details aren’t dished out to a crowd of financiers. Please fill in the form accurately, especially the order size, your customer type and your timing, so the first conversation can get straight to the right structure. Tell us about your order.
The 1-2-3, in short
- 1
Get the order in writing
A signed purchase order or contract from a reliable customer is the foundation of the whole deal.
- 2
Line up the supplier
Confirm price, quantity, quality and delivery dates. A late or faulty delivery puts the whole chain at risk.
- 3
Map the cash timeline
When the supplier is paid, when goods arrive, when you invoice and when the customer pays. Fund the gap with a buffer.
Frequently asked questions
How is purchase order finance different from invoice finance?
Purchase order finance funds the supplier before the goods are delivered. Invoice finance unlocks money after you've delivered and invoiced. Some businesses use both: one to fill the order, the other to wait less for payment.
Does my business need a long trading history?
Less than for some loans, because the financier focuses on the order and the customer. That said, your track record of delivering similar orders still matters.
What kinds of businesses use purchase order finance?
Usually distributors, wholesalers, importers and resellers who buy finished goods and on-sell them. It's less suited to businesses that heavily transform materials, because there are more steps between supplier and customer.
What if my customer cancels the order?
That's the core risk. Read the customer contract carefully, understand cancellation terms and consider how you'd sell the stock elsewhere if needed.